Categories
Arizona Home OwnersPublished October 18, 2026
Why Your Monthly Payment Matters More Than the Interest Rate
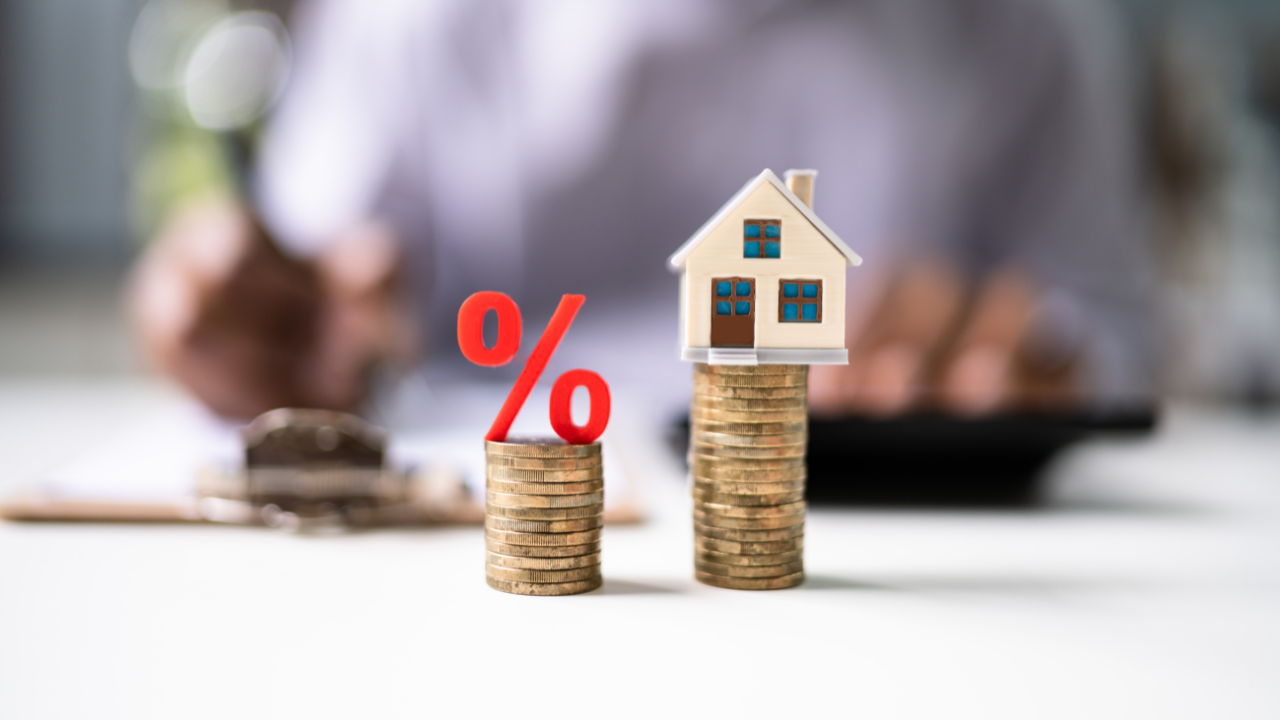
Everyone is waiting for rates to fall, but that's the number no one can promise. The payment is the part you can actually shape, and there are real ways to bring it down.
The question on everyone's mind is the same: when will interest rates finally come down? It's a reasonable thing to wonder. But it may be the wrong question to build a decision around, because the rate is only a number, and the number you actually live with every month is your payment.
Rates move on forces no one in this conversation controls. Mortgage rates are tied to far bigger things than any one person's timeline, from global conflict and gas prices to inflation and the bond market.
It's worth remembering, too, that the Federal Reserve doesn't set mortgage rates directly. The Fed controls short-term borrowing costs, while mortgage rates track the longer end of the bond market, which is why they don't always move the way the headlines suggest. The takeaway for a buyer or seller is simple: building your plans around a quick drop in rates is building them on something no one can promise.
The conversation that actually matters is affordability. Shifting the question from 'what's the rate' to 'what's the payment, and can I live with it comfortably' changes everything. Two buyers can purchase the same home at the same rate and have very different experiences, because one shaped the payment to fit their life and the other simply accepted the first number they were handed. The payment is the part you can influence.
"Don't plan your life around a rate that may never drop. Plan around the payment, because that's the part you can actually shape."
There are real ways to bring that payment down. Depending on your situation, there are strategies to lower your rate, in some cases into the fours. A rate buydown is one of the most effective, and it's a tool sellers should understand too: offering to help buy down a buyer's rate often does more for the buyer than an equivalent price reduction, and it can help a listing stand out.
One move worth approaching carefully is the adjustable-rate mortgage. The experience of homeowners who took an ARM several years ago and are now facing their adjustment is a useful reminder that a lower payment today can become a larger problem later.
Remember that your payment is more than principal and interest. Taxes and insurance are part of it, and homeowner's insurance costs in particular have been rising. Planning for those costs, and locking them in where you can, belongs in any honest affordability conversation, because they shape the payment just as much as the rate does.
For buyers, the current market carries a quiet advantage. Higher payments have cooled competition, which means fewer bidding wars, more room to negotiate, and sellers who are often willing to work with you. The buyers who come out ahead in this market aren't the ones waiting on the sidelines for rates to fall. They're the ones who ran real numbers and moved with a plan.
If you're weighing a move, call or text me at (480) 415-1341, email me at Katie@living48re.com, or visit living48realestate.com. We'll run your real numbers and build a plan around the payment you can actually live with.
Let's focus on what you can control, and leave the guessing about rates to the headlines.
Katie Evans
Lead Agent | Katie Evans | Living 48 Real Estate Team
or another way